Written by : Dr Chris D’Souza – Deputy CEO and CFO of of ICMA (ANZ).
The Man at the Check-In Desk
Part One showed that customers often focus on price because businesses fail to make the value they deliver visible. But recognising this problem is only the beginning. The real challenge is how businesses create that value and demonstrate it to customers.
A chance conversation at Melbourne Airport brought this challenge into sharp focus. The Thai Airways representative greeted me as a Platinum member and asked what was taking me away. I told him I was going to deliver the CMA program. He asked what that was, and then surprised me: he wants to start his own business, and asked what he should focus on.
I told him what I would tell anybody: focus on the value you are creating, and the price will take care of itself. A business, as the CMA program teaches, has three things to balance, cost, quality and time, and a fourth that most people leave out, innovation.
I have been thinking about that answer ever since. Cost sits on the price side of the ledger. It is what you incur, and it determines the price at which you can survive. Quality and time shape what customers experience, while innovation creates new ways of delivering value. Together, they are the value drivers that influence the price you can command.
Cost, quality and time are usually described as a trade-off, and in the ordinary course of things they are. Cheap and fast is rarely good. Good and fast is rarely cheap. Innovation is what allows businesses to break that trade-off, improving cost, quality and speed together. The shipping container did it for freight. The Toyota production system did it for manufacturing. Innovation is the lever. The other three are the constraints it has to work within.
But innovation is often among the first things cut when times are hard, because it is pure cost clearly visible today with a potential value not visible until much later. The cost shows in this year’s accounts. The value does not.
The Firms That Made Price Go Quiet
That sounds like easy advice to give at a check-in desk. So let me show you businesses that have actually done it. What is interesting about them is not that they are large or famous. It is that each one arrived at the same result by a completely different route, which tells you there is no single formula here.
Emirates Airlines has almost never been the cheapest fare on any route it flies, and it is almost never asked to justify the difference. The value is service, delivered consistently for decades, so that a passenger booking a flight is not comparing two airline seats. They are comparing an experience they trust against one they do not know, and they pay for the one they trust.
Amazon is the company most associated with low prices anywhere in the world, yet it was very often not the cheapest place to buy anything. What it built was a seamless shopping experience: providing the products customers wanted, on demand. That value was so visible and so reliable that people simply stopped checking whether the price was the best available.
And you do not need to be either of them to do it. As I described in Part One, my own small firm in Mumbai held its ground against the largest accounting firms in the world, with none of their resources or reputation, simply by delivering work that could withstand examination.
The pattern is the same in all three. None won an argument about price. Each started with the customer, worked out what they actually needed, built the business around delivering it, and then made sure the customer could see it. Once the customer could see it, the price became a detail to be settled rather than a battle to be fought. Scale is not the mechanism. Visibility is.
Where This Argument Stops
I have been pushing in one direction long enough that I should mark the boundary, because an argument that applies everywhere usually applies nowhere.
Some things really are commodities. If you sell screws or cement or bandwidth to a specification anybody can meet, no amount of storytelling will persuade a buyer to pay more for yours. Smith’s (1776) point about scarcity cuts both ways. Abundance sets the price, and visibility does not change that.
Formal procurement is a second boundary. Where a panel scores tenders against published criteria, value has to be expressed in the categories the panel will accept, or for that purpose it does not exist at all. Persuading the panel to change its criteria is a different and much slower project than persuading a buyer across a table.
And some customers genuinely cannot pay for value, because their own margins leave them nothing to pay it with. Telling such a buyer to look past the price is not insight. It is indifference to their position.
The test is whether your customer can see a difference in what you do, is free to act on it, and can afford to pay for it. Where all three hold, everything in this article applies. Where they do not, the honest response is to adapt what you offer and what you charge to the customer’s constraints, rather than insist on a premium they cannot justify or afford.
What Canon Did to Xerox
One example shows all of this at work, through a technique we teach that is routinely misunderstood, including, until recently, by me. The account draws on Canon’s own published history and on Yamanouchi (1989).
For years Xerox owned the plain paper copier. Its machines were large and expensive, sat in a central room, and came with a service network that was itself a barrier to competitors. Xerox followed the conventional cost-plus approach: build the machine, work out the cost, add the margin.
Canon began at the other end. It looked at customers Xerox was not serving, people who wanted a small copier beside their own desk, and asked what that convenience was worth to them. That gave Canon a price before it had designed anything. It then subtracted the margin it needed, and what remained was not an estimate of cost. It was an instruction: design a machine that costs this.
That constraint produced the all-in-one cartridge, combining drum and toner, which the user could change without a technician. The PC-10 and PC-20 reached the market in May 1982 at under a thousand dollars, against four or five thousand for a conventional office copier.
Xerox could see precisely what Canon had done and still could not follow. Its factories, sales force and much of its revenue rested on machines that needed servicing. To copy Canon, it would have had to dismantle the very thing that had made it dominant. Canon had not simply built a cheaper copier. It had turned Xerox’s greatest competitive advantage into a costly liability.
That is target costing. I have heard it described, and have described it myself, as what a business falls back on when it has lost control of its price. That is wrong. It is the technique that most clearly puts value first and cost last: what the customer values, then what they will pay, and only then what we are permitted to spend.
Once You See It, You See It Everywhere
“Not everything that can be counted counts, and not everything that counts can be counted.” Cameron (1963)
Canon is not an isolated case, and target costing is not an isolated technique. Almost every technique in the CMA program exists for one reason: something that mattered a great deal was not showing up in the accounts, and somebody set out to drag it into view.
Cost of quality exists because nobody receives an invoice for poor quality. There is no bill for the customer who did not come back, so we built a way to put a number on it.
Activity based costing and activity based management exist because overhead hides where the money goes. They strip the averages away and show which products and activities are really consuming the resources.
Life cycle costing exists because the purchase price is loud and the twenty years afterwards are silent. It lets a buyer see the whole stream instead of the first payment.
Customer profitability analysis exists because a large invoice looks like a good customer. It makes visible the returns, the rework, the special handling and the hours your people quietly give away, and it regularly names your favourite client as your most expensive one.
Environmental and social accounting exists because the cheapest goods often carry a cost that somebody else, somewhere else, is paying in full. It puts that cost back on the page where the decision is being made.
Business valuation exists because a share price is not a value. The distinction between the value game and the pricing game is Damodaran’s (2017), and confusing the two is among the most expensive mistakes in finance.
Every one of these makes something invisible visible, and we are very good at it. Financial accounting reports what happened. We exist to reveal what would otherwise never be seen.
Which makes it remarkable how little of it we have turned on the one thing that decides whether a business survives. We can tell you what a customer costs to serve, down to the activity. What they receive we measure crudely, inconsistently, and almost always outside the management accounts. That gap sits in the middle of our own discipline.
What We Might Actually Measure
Let me show what closing that gap might look like. This is a starting point offered for argument, not a method I am proposing we adopt.
Customer profitability analysis already gives us cost to serve, by customer. Set four columns beside it, none needing machinery we do not already own.
What they came back for. Repeat purchase by customer, by line, over time. Almost every firm holds this data and almost none reads it as a measure of value received.
What they brought with them. Referrals traced to source. A customer who sends other people has staked their own standing on your work, a stronger statement than any survey response. Earlier this year a participant from our Jakarta program persuaded two friends to enrol in Bangkok a fortnight later, and one of them flew in from Dubai. Nobody asked him to. Nothing in our accounts records that he did.
What they would otherwise have done. The next best alternative available to that customer, and what it would have cost them in money and time. This is an economic value calculation, not a sentiment, and it is arithmetic we already know.
When they stopped comparing. A customer who returns without seeking competing quotes provides a strong signal that value has become visible to them.
None of that is a valuation, and I would not defend any single column against a determined critic. But a firm that kept those four beside cost to serve would know something about its customers that very few firms know. It would be doing with value what we have already done six times over with cost.
Before Anybody Quotes Me Approvingly
There is a dangerous version of this argument. “Value, not price” is also the catchcry of every overpriced product with a thin story behind it. Charging a premium is not the same as being worth one. With nothing underneath, it is simply extraction dressed up in better language. Every one of us has bought something expensive that turned out to be nothing more than expensive, and none of us went back.
So how do you tell the difference when you are the one setting the price? The most honest test is repeat purchase. If your customers come back and bring other people with them, that is strong evidence that the value was real and that they received it. If they do not, you have reason to question whether the value you believed you were delivering actually reached them, whatever your margins looked like in the meantime.
One qualification. Repeat purchase proves less where switching costs are high, and my own iPhone is the obvious example. Photographs, messages, applications and payment details all sit inside one ecosystem, and moving them is a real cost that has nothing to do with the merits of the next handset. So the test needs a second question beside it: would this customer still come back if leaving cost them nothing? Where the honest answer is no, some part of what you are collecting is rent rather than value.
A business with fat margins and high churn may have worked out how to charge a premium without working out how to earn one. It usually discovers this too late. This is precisely why the subject cannot be left to marketing alone. Somebody has to do the counting.
Three Questions for Your Own Organisation
These three questions are simple, and in my experience most firms never ask them.
First, what exactly is the value we deliver, and has a customer ever heard us describe it? Not what we sell or what we make, but what they walk away with. If we cannot articulate it clearly, we cannot expect our customers to recognise it.
Second, what have we given our customers to care about besides our price? If the honest answer is nothing, then the price objection we keep hearing is not their failing. It is ours, and it is entirely fixable.
Third, would anybody get on a plane for us? Is there anything in this business that a customer would spend their time, and not merely their money, to be near? And if there is, does it have a name, and do we publish it?
The First Flight
I promised in Part One that I would come back to an earlier flight, and this is it.
Over two decades ago I was running my firm in Mumbai and had almost no spare time. Then the CMA program came along, and to do it I had to fly to Delhi and stay in a hotel for the duration. The money was real enough. The time was by far the larger part of the price.
I went anyway, and the reason is the point of this article. It was not the syllabus, which I could have read at home in Mumbai for nothing. I went because Professor Janek Ratnatunga was going to be in that room, and I wanted to be in the room with him.
What I learnt and experienced over those days was worth the fare several times over, but the moment I remember is a smaller one. Professor Ratnatunga asked whether he might take my CV back to Australia with him. Everything that has happened to me since began in that question, and I had no idea of it at the time.
But notice that none of this value existed when I decided to go. It was all in the future and completely unproven. All I had in front of me was a price I could see clearly and one good reason to look past it. That is the position a new customer is in every time they consider buying from you. They cannot see your value, because it has not happened to them yet. They can only see your price, and whatever else you have been thoughtful enough to place beside it.
I paid a substantial price over two decades ago. The value has never stopped paying. It taught me to look at my own firm properly for the first time. It is the reason I could afford to fly home to Melbourne when my grandson was born. It is the reason people ask me to stand in front of rooms from Melbourne to Jakarta to Bangkok to Dubai and even as far away as Canada, which is also, awkwardly, the reason I am on this aircraft instead of at home cuddling my Ari.
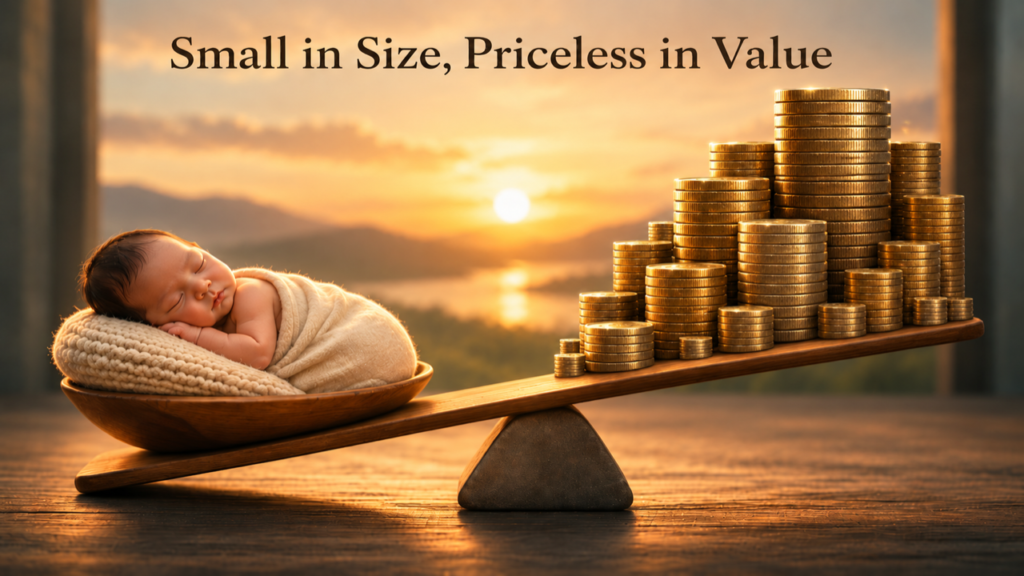
So twice in my life I have paid heavily, in time and money, simply to be in a room with one particular person. Once for a world-renowned professor, Janek Ratnatunga. Once for my tiny grandson Ari, who inspired this article: small in size, priceless in value. Both times what I was really buying was presence, and both times the value I received was infinitely more than the price I paid.
There is a lesson in that for any business. Price matters least when the something else you offer is more valuable than the money the customer is paying. Often that value is provided by a person. It is why patients choose the surgeon and not the hospital, why clients choose the barrister and not the firm, why parents choose the teacher and not the school. Most organisations market the firm, and then wonder why the client wants to talk about the fee.
The Third Flight
So, there have been two flights, two decades apart: one to Delhi, to sit in a room with a man I had never met, and one to Melbourne, to sit in a room with a child who cannot yet say my name. Now there is a third, and I am on it as I write, on my way to a month of programs in Jakarta and then Bangkok.
The strange thing about this flight is that it has almost no price, in the sense any accountant would recognise. The fare is the back half of the ticket that carried me home to Melbourne, already reconciled, coded and filed by somebody who is very good at that job. There is a hotel at the other end. The money side of this journey is a modest figure that already sits in a ledger, settled.
So what are these four weeks actually costing me?
All of it sits on the other side, and not a line of it will ever be recorded. I will miss four weeks of the very beginning of somebody’s life. Ari will change more in these four weeks than in almost any four that follow, and I will see none of it. It is by a distance the most expensive thing I will spend this year, and it will not appear in a single set of accounts, mine or anybody else’s.
That is the argument of both parts of this article, sitting in one seat on one aircraft. The visible half is settled and filed. The other half is written down nowhere, and I am paying it right now.
The bills will keep arriving and the flinch will not go away. It is a human reaction. But the flinch is a response to the only number on the page, and there is always more to the purchase than the number. Your customer is standing exactly where I stood at both of those departure gates. So give them something else to look at, and make certain that it is real when they get there.
Ari cannot say my name yet. He already carries it, though. His parents gave him Christopher as his second name, and it is the most valuable thing I have ever been given. Nothing changed hands. No figure was discussed. There is a form in a registry office somewhere and that is the entire paper trail.
He cannot see what that name is worth yet. Nobody could, at a week old. By the time he can say it, I intend to have made it worth carrying.
References
Cameron, W. B. (1963) Informal Sociology: A Casual Introduction to Sociological Thinking. New York: Random House, p. 13.
Damodaran, A. (2017) Narrative and Numbers: The Value of Stories in Business. New York: Columbia University Press.
Smith, A. (1776) An Inquiry into the Nature and Causes of the Wealth of Nations. Book I, Chapter IV. London: W. Strahan and T. Cadell.
Yamanouchi, T. (1989) ‘Breakthrough: the development of the Canon personal copier’, Long Range Planning. Reprinted in Kono, T. (ed.) (1992) Strategic Management in Japanese Companies. Oxford: Pergamon Press.
Dr Chris D’Souza is Deputy CEO of CMA Australia and New Zealand